Investment
The Crest at Newquay: Investment Case, Yield Arithmetic and Due-Diligence Questions for a UK Apart-Hotel
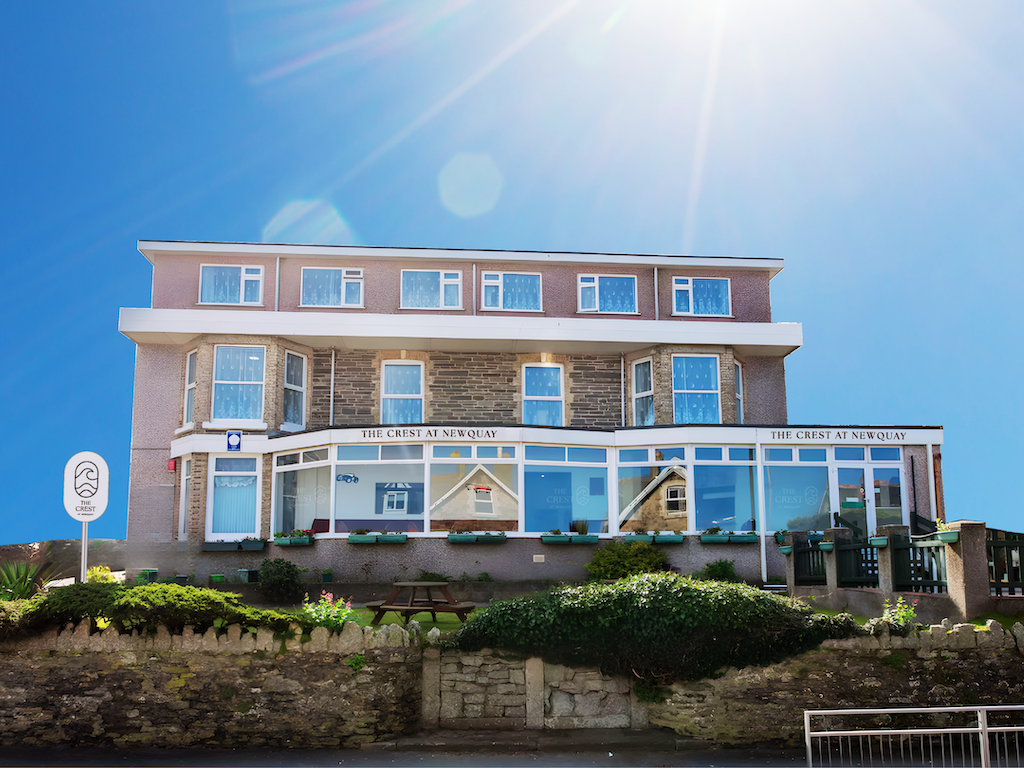
The Crest at Newquay: Investment Case, Yield Arithmetic and Due-Diligence Questions for a UK Apart-Hotel
A research note for investors weighing a cash-purchase UK apart-hotel unit: what is being offered, what the headline yield assumes, and the legal, regulatory and seasonal questions to settle first. To discuss the opportunity, use the Murivest private enquiry form.
Executive Summary
The Crest at Newquay is a boutique apart-hotel near Towan Beach in Cornwall. Its marketing partner, Opulent Invest, offers units on a cash-only basis from £74,950, with a projected net yield of up to 15% and no stamp duty. Those are attractive headlines. They are also assumptions, and an investor's task is to find out which assumptions they rest on.
This note reviews the claims against primary sources. Stamp duty may well be nil, but the classification depends on how the unit is legally held and used. The yield is plausible only if a small unit earns revenue close to or above the average of the local short-stay market, so the note sets out the revenue each target yield requires. Seasonality is material: Cornwall Council puts 67% of Newquay's visitors in April to September. And because income from rooms in a managed hotel can resemble a pooled scheme, regulatory status is a question every buyer should ask. The note ends with a five-point check and ten questions. It is research, not advice, and you can request information on the opportunity here.
By Private Enquiry
Discuss The Crest at Newquay
Tell us your budget, residency and objectives. We will respond with the information available and the due-diligence questions to put to the seller, before you commit any capital.
A request for information, not an offer. No obligation. Capital is at risk.
What Is Actually Being Offered
The development has been promoted by more than one firm, and the published terms differ. That is the first due-diligence finding.
| Source | Entry price stated | Yield and tax claims |
|---|---|---|
| Opulent Invest, blog post dated 28 September 2026 | From £74,950, cash purchase | Projected net yield up to 15%; zero stamp duty; zero ground rent |
| Opulent Invest, listing page | Fully managed apart-hotel from £72,950 | Cites a Newquay short-stay sample: average daily rate £120, occupancy 40%, about 1,000 listings |
| Quartico, development page (undated) | From £44,950 for a single room; £72,950 to £84,950 twin or double; £99,950 deluxe | Projected 15% net; stamp duty described as exempt |
Sources: Opulent Invest blog, Opulent Invest listing, Quartico. Prices and terms may have changed; confirm the current unit price list in writing.
The differences may reflect unit types, release phases or the date of each page, but a buyer should not assume so. Ask which unit the "from" price refers to, whether the 15% applies to that unit, and what it is net of. The offering is structured as an operated apart-hotel in which the investor receives income rather than running the unit. The key legal questions follow from that, and are covered below.
The Argument: A Headline Yield Is a Hypothesis to Be Tested
A "projected net yield of up to 15%" contains three separate claims: that the unit will earn a certain revenue, that a certain share will be left after costs, and that the remainder will actually reach the investor. Each can be tested. Few buyers do, because the headline is persuasive and the documents are long.
Reading the evidence: "Up to" is the operative phrase. The question for an investor is not whether 15% is possible, but what must be true for it to happen, and how likely each of those conditions is.
If you want a specific unit examined in these terms, send the details through our enquiry form.
Stamp Duty: Probably Nil, But Proof Matters
The claim of zero stamp duty has a legal basis. Section 116(3)(f) of the Finance Act 2003 provides that a hotel or inn or similar establishment is not residential property for Stamp Duty Land Tax, and HMRC's manual confirms that this applies even where a building would otherwise be suitable as a dwelling (legislation.gov.uk; HMRC SDLT Manual). Non-residential purchases carry a nil-rate band up to £150,000, which would cover every unit price quoted above (GOV.UK).
Two cautions apply. First, classification turns on facts. In Hurst v HMRC [2024] UKFTT 540 (TC), the First-tier Tribunal applied a multifactorial assessment of whether a property was used as a hotel or similar establishment, and decided the case in the taxpayer's favour only narrowly (judgment). A label in a brochure does not settle the question; the legal structure of the unit and its actual use do. Second, stamp duty is one cost among several. Ask your solicitor whether VAT is chargeable on the price, what legal and registration costs apply, and what happens if HMRC disagrees with the classification after completion.
Regulation: Is Income From a Managed Room a Collective Investment Scheme?
This question is the one most often skipped. Under section 235 of the Financial Services and Markets Act 2000, a collective investment scheme exists where arrangements enable participants to receive profits or income from property, where contributions and income are pooled, and where the property is managed as a whole by or for an operator (the statutory definition is set out in FSA v Asset L I Inc). Arrangements of that kind generally require authorisation or an exemption, and promoting them is restricted by section 21 of the same Act.
The regulator has been explicit about the area. The Financial Conduct Authority has warned that holiday-lodge and holiday-home investment schemes promoted by unauthorised firms may be unregulated collective investment schemes, that they may be unlawful and high risk, and that investors in them are unlikely to have access to the Financial Ombudsman Service or the Financial Services Compensation Scheme (FCA statement). In FCA v Forster, the High Court considered a model in which investors bought leasehold interests in rooms in care homes, student accommodation and hotels, with promised guaranteed rents and buy-back terms (judgment).
None of this says that The Crest is a collective investment scheme, and we make no such claim. Whether a given offering is one depends on its documents: whether income is pooled, whether the investor has day-to-day control of the unit, and who operates it. The point is that the question is legitimate and answerable. Ask for the operator's legal identity, for written confirmation of the regulatory position from the seller's solicitors, and check any firm involved on the FCA Register. If you want help framing those questions, start with our enquiry form.
Yield Arithmetic: What Revenue Does 15% Require?
The most useful exercise is to work backwards. The following is a hypothetical illustration, not a forecast and not a statement about any specific unit.
Assumptions. Purchase price £74,950. "Cost ratio" means the share of gross room revenue consumed by operator fees, housekeeping, utilities, service charges, insurance and other costs before the investor's share. Purchase costs and tax are excluded. Occupancy is taken at 40%, the figure Opulent cites for the Newquay sample.
| Target net yield (net income) | Cost ratio | Revenue needed per year | Daily rate needed at 40% occupancy |
|---|---|---|---|
| 15% (about £11,242) | 35% | about £17,296 | about £118 |
| 50% | about £22,485 | about £154 | |
| 60% | about £28,106 | about £193 | |
| 10% (about £7,495) | 35% | about £11,531 | about £79 |
| 50% | about £14,990 | about £103 | |
| 60% | about £18,738 | about £128 | |
| 7% (about £5,247) | 35% | about £8,072 | about £55 |
| 50% | about £10,493 | about £72 | |
| 60% | about £13,116 | about £90 |
Now compare these requirements with the market sample Opulent cites. An average daily rate of £120 at 40% occupancy yields about £17,520 a year, or £1,460 a month. Opulent's stated average monthly revenue of £2,100 would be £25,200 a year. These two figures do not reconcile: £2,100 a month at a £120 rate implies occupancy near 58%, not 40%. They may come from different samples or definitions, and the discrepancy should be put to the seller.
The reading is straightforward. If costs take about 35% of revenue, 15% is reachable at the sample's rate and occupancy. If costs take half, the unit needs about £154 a night at 40% occupancy, or roughly 51% occupancy at £120. The sample covers about 1,000 listings of mixed size, and a small studio is not necessarily an average listing. A 15% projection therefore depends heavily on the cost ratio, which is the number least visible in marketing material. Ask for the fee schedule and a worked income statement for the specific unit, and for actual trading history if the hotel is already operating. To request those documents, use the enquiry form here.
Before You Reserve
Test the Yield Against Your Own Assumptions
If the numbers above raise questions about a specific unit, send them through. Ask for the unit price list, the fee schedule and the operator agreement, and review them with your own solicitor.
Murivest does not provide regulated investment advice. Independent legal and tax advice is essential.
Location and Seasonality
Newquay has genuine strengths: beaches, an established surf and short-break market, and a large visitor base. Operators told The Caterer in 2026 that staycation bookings were rising sharply, with one reporting average length of stay up from 1.9 to 2.3 nights, and attributing part of the surge to events overseas (The Caterer). Demand that rises on external events can fall when they pass, so it should not be extrapolated.
Opulent states that Newquay was named the top emerging UK staycation destination for 2026, with bookings up 32.5% year on year. We could not locate the original source for that claim and have not verified it. Treat it as a marketing statement until the source is produced.
Seasonality is documented. Cornwall Council reported that the peak months of April to September account for 67% of Newquay's visitors, and described a UK Shared Prosperity Fund project to extend the season into winter (Cornwall Council). The council's figure dates from that project's announcement, and the project was scheduled to run until March 2025, so current seasonality should be confirmed. For an investor, the practical meaning is that an annual figure built on the summer peak will overstate a typical month. Ask for a monthly income profile, not an annual average.
The Renters' Rights Act: What It Does and Does Not Change
The Renters' Rights Act 2025 came into force on 1 May 2026 in England. GOV.UK guidance states that a tenancy will not be an assured periodic tenancy where the property is a holiday let, a business tenancy or licensed premises (GOV.UK). Apart-hotel guests on genuine short stays therefore sit outside the regime, which is a real structural difference from buy-to-let.
The exclusion is not automatic for every arrangement, however. Law-firm commentary notes that lettings genuinely made for holiday purposes are excluded, but that arrangements dressed up as holiday lets may be treated as assured tenancies where the same person occupies on a repeat or long-term basis, which can matter in longer winter lets (Freeths). If an operator responds to winter seasonality by offering longer stays, the legal character of those stays deserves attention.
The Murivest Apart-Hotel Five-Point Check
The Five-Point Check is a Murivest-developed analytical tool. It is not a regulatory test, has not been independently validated and does not rate any investment. It is a set of questions to answer in writing before paying a reservation fee.

- What do I own? A registered leasehold of a specific room, shares, or a contractual right? What is the lease length, and is there ground rent or a service charge?
- Who operates it, and is income pooled? Identify the operator, the management agreement, its term and termination rights, and whether income from all rooms is shared. Ask for written regulatory advice.
- What does "net" mean? Obtain the fee schedule and a worked income statement. Check that the yield is net to you, after every cost.
- What happens in a weak year? Ask for the monthly income profile, the downside case and whether any return is guaranteed. If one is, ask who stands behind the guarantee.
- How do I exit? Ask about resale of similar units, restrictions on transfer, and any buy-back promise, including who funds it. Cash-only units have a narrower buyer pool, because buyers cannot use a standard mortgage.
Questions you cannot get answered in writing are risks until evidenced. Ask Murivest for help assembling the documents.
Who Might Consider It, and Who Probably Should Not
The profile that fits is an investor with cash available, comfortable with seasonal and variable income, wanting a managed asset in the leisure sector alongside other holdings, and willing to read the operator agreement in full. The profile that does not fit includes anyone who needs mortgage finance, who needs predictable monthly income, who has not taken legal and tax advice, or who would struggle if the unit earned materially less than projected. A non-UK investor should add sterling exposure and UK tax on income to the checklist. Our companion note for Nairobi-based investors, Kenyan Investors and UK Real Estate from KSh 3.5 Million, sets out the currency and structure questions in detail.
The Reported Opportunity at a Glance
The block below summarises what the promoters publish. It is not a Murivest listing or an offer, and the figures are the promoters' own.
REPORTED OFFERING: The Crest at Newquay
Location: Newquay, Cornwall, close to Towan Beach
Entry price stated: from £72,950 to £74,950 depending on the source; cash purchase only
Structure: Operated apart-hotel units; investor receives income, not day-to-day management
Claims cited: projected net yield up to 15% (a projection, not a guarantee); zero stamp duty (subject to classification)

To discuss this or other UK opportunities against your own criteria, submit a private enquiry.
Ten Questions to Settle Before Reserving a Unit
- What exactly is the legal interest I would acquire, and in which unit?
- What is the current price list, and why do published entry prices differ between promoters?
- Who is the operator, and what are the management agreement terms?
- Is income pooled, and what is the written regulatory position?
- What is the cost ratio, and can I see a worked income statement?
- What is the actual trading history, by month?
- Is any return guaranteed, and who backs the guarantee?
- Is VAT chargeable, and has the stamp duty classification been confirmed in writing?
- What happens if the operator fails or the agreement ends?
- How would I sell, to whom, and at what likely discount?
Frequently Asked Questions
What is The Crest at Newquay?
It is an apart-hotel near Towan Beach in Newquay, Cornwall, promoted to investors as fully managed units on a cash-only basis. Published entry prices range from £72,950 to £74,950 depending on the source, with a projected net yield of up to 15%.
Is the 15% net yield guaranteed?
No. It is a projection, described by the promoters as up to 15%. Whether it is reached depends on revenue and on the share of revenue consumed by costs. The break-even table above shows how sensitive the result is.
Do apart-hotel units attract stamp duty?
Hotels and similar establishments are not residential property for Stamp Duty Land Tax, and non-residential purchases carry a nil-rate band up to £150,000. Classification depends on the facts, so a solicitor should confirm it for the specific unit before exchange.
Is investing in a hotel room a regulated investment?
It can be, depending on structure. Arrangements where income is pooled and the property is managed as a whole by an operator can amount to a collective investment scheme, which generally needs authorisation or an exemption. Ask for written advice and check firms on the FCA Register.
Does the Renters' Rights Act affect apart-hotel investors?
The Act, in force since 1 May 2026, excludes genuine holiday lets and licensed premises from the assured tenancy regime. The exclusion depends on the stays being genuinely short and for holiday purposes, so longer repeat stays warrant legal advice.
Methodology, Disclosure and Limitations
This note was prepared on 14 October 2026. Facts about The Crest are drawn from the promoters' own published pages, dated as stated, and have not been independently verified. Legal and tax points are taken from legislation.gov.uk, HMRC, GOV.UK, the First-tier Tribunal and the FCA, each linked. Seasonality data come from Cornwall Council; staycation commentary comes from The Caterer. The yield table is hypothetical, uses stated assumptions and is not a forecast.
The unit-level information above is the promoters' own and has not been verified by Murivest. The Murivest Apart-Hotel Five-Point Check is an internally developed framework, not a regulatory standard and not independently validated. Murivest was established in 2025 and describes its role only to the extent it can evidence it.
Sources and Further Reading
- Opulent Invest, The Crest at Newquay: Investment Case (28 September 2026)
- Opulent Invest, The Crest at Newquay listing
- Quartico, The Crest at Newquay
- Finance Act 2003, section 116
- HMRC, SDLT Manual SDLTM30070
- GOV.UK, SDLT rates for non-residential and mixed land and property
- Hurst v HMRC [2024] UKFTT 540 (TC)
- FCA, Beware of unregulated holiday park investment schemes
- FCA v Forster and others [2023] EWHC 1973 (Ch)
- FSA v Asset L I Inc [2013] EWHC 178 (Ch)
- Cornwall Council, Experience Newquay funding announcement
- The Caterer, UK hotels report boost in leisure demand
- GOV.UK, Tenancy types
- Freeths, Renters' Rights Act and rural lettings
Your Next Step
An Informed Conversation Comes First
Whether you are in London, Nairobi or elsewhere, the sensible first step is to understand the legal right you would hold and who pays you. Start your enquiry privately.
Begin Your EnquiryRead the UK Hub
Eligibility, identity and source-of-funds checks may apply.
Regards,
Murivest Research Desk
Murivest Group Ltd
October 2026
P.S. Before you pay any reservation fee, get the operator agreement, the fee schedule and the regulatory position in writing. Ask us to help you assemble them.
Related Articles
- Kenyan Investors and UK Real Estate from KSh 3.5 Million
- How to Buy Commercial Property in the UK: A Seven-Gate Due-Diligence Framework for Overseas Investors
- UK Office Rental Income and Flexible Workspace
- Murivest UK: Commercial Real Estate Investment and Capital Markets
Important investment disclosure: This article is for general research and educational purposes and does not constitute personalised investment, legal, tax or financial advice, an offer to sell any investment, or a guarantee of performance. Murivest Group Ltd is an independent real estate advisory firm. We do not act as a licensed investment advisor and do not offer regulated financial products or collective investment schemes. We do not pool capital from multiple investors. All advisory engagements are mandate-based, subject to formal documentation, comprehensive KYC/AML verification, and explicit scope definition. Opportunities described as reported are attributed to third-party sources and are not Murivest offers. Projected yields are not guaranteed, rental income can fall, and capital is at risk. Investors in unauthorised or unregulated schemes may be unable to access the Financial Ombudsman Service or the Financial Services Compensation Scheme. Prospective investors should review the complete offering documents and take independent legal, tax and financial advice. Past advisory outcomes do not guarantee future results.
Related Reading
Investment
Diani and Watamu Land have appreciated by 400% since 2020
9 min read
Investment
UK Office Space Investment Outlook 2026: Where Capital Can Still Find Income as Prices Reset
17 min read
Investment
How to Buy Commercial Property in the UK: A Seven-Gate Due-Diligence Framework for Overseas Investors
18 min read
Murivest Community
Investor Discussion
Discuss investment opportunities, market trends, lease activity, financing, and underwriting with the Murivest community.
Join the Discussion
Share investment insights, market commentary, or leasing observations.
Professional discussion only. All comments are moderated.
Loading…
No discussion yet — be the first to contribute an insight.
Ask Murivest Research
Submit a Research Question
Questions on underwriting, leasing, market fundamentals, or capital structures are answered by the Murivest desk.
Murivest Research